Starting from July 1, 2024, borrowers who have completed three years from the date of disbursement will transition from a Semi-Fixed Rate of Interest to a Fully Fixed Rate of Interest, as outlined in the Loan Agreement.
.
This means your interest rate will remain constant for the rest of your loan term, offering you greater predictability and stability in your financial planning.
As per the RBI notification dated November 12, 2021, the following guidelines are in effect regarding the classification of Non-Performing Assets (NPA):
| Standard Account: | No overdue payments. |
|---|---|
| Special Mention Account (SMA): |
|
| Non-Performing Asset (NPA): | 90+ days overdue |
Due Date
31 March 2021
Overdue Date
31 March 2021
(if full payment not received by day-end)
April 30, 2021
Classified as SMA 1
(30 days overdue)
May 30, 2021
Classified as SMA 2
(60 days overdue)
June 29, 2021
Classified as NPA
(90 days overdue)
Important: To avoid legal action and maintain a good credit record, please ensure all overdue payments are cleared promptly.
In the unfortunate event of a borrower's demise, legal heirs can retrieve the original title documents by following our established procedure.
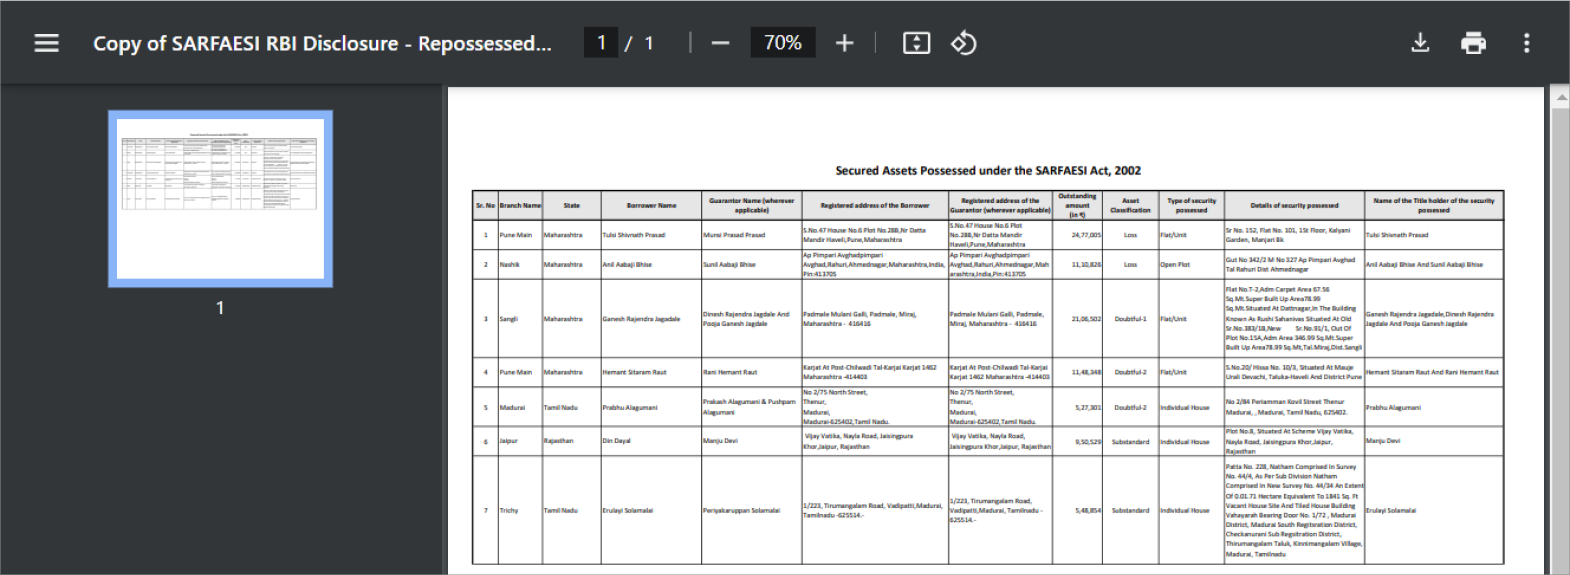
We have a list of repossessed properties available. Please refer to the PDF linked below for detailed information: